Storm Damage Restoration in Bryan: What Your Insurance Covers
Most Bryan storm damage claims get paid - but only when the loss is documented right. Here's exactly what Texas policies cover, what they don't, and what restoration costs in 2026.
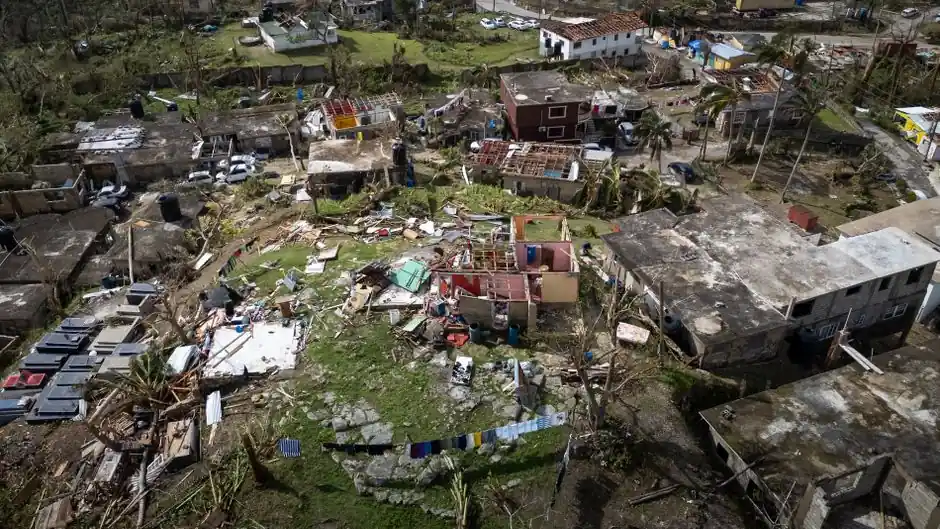
Yes - most storm damage restoration in Bryan what your insurance covers comes down to one rule: if the storm caused it, your policy usually pays. Homeowners policies in Texas cover wind, hail, falling limbs, and the rain that gets inside after your roof or windows fail. Storm damage restoration in Bryan what your insurance covers is a category of covered loss that includes water extraction, structural drying, roof leak repair, and the rebuild that follows - minus your deductible and any damage the policy specifically excludes.
What follows is the part most homeowners never get told before they file: what Texas policies actually pay for, what they fight you on, what restoration costs in Bryan in 2026, and how to document a claim so it doesn't get cut in half.
Does insurance cover storm damage restoration in Bryan TX?
Storm damage restoration is covered in Bryan TX when the damage is sudden and accidental - a hail strike, a wind gust, a tree limb through the deck, or rain driven in through a failed roof. Standard HO-3 and HO-5 policies, which is what most Bryan homeowners carry, treat these as named perils. The storm happens, you file, the carrier pays to return the house to its pre-storm condition.
The exception is flood. Water that rises from the ground - creek overflow, street flooding, a swollen drainage ditch backing into your slab - is excluded from every standard homeowners policy in Texas. That damage requires a separate NFIP or private flood policy. If your neighborhood sits near Still Creek, Carter Creek, or the low spots along Villa Maria, this distinction matters more than anything else in your policy.
We handle both sides of that line every week. When a storm pushes water through a failed roof, that's a covered claim and we document it as one. When it comes up through the floor drain, we tell you straight that it's a flood claim before you waste a week on the wrong adjuster.
What storm damage insurance covers in Bryan Texas
Storm damage insurance coverage in Bryan Texas typically pays for four buckets of work: emergency mitigation, structural drying, repairs, and contents. Here's what each one actually includes.
Emergency mitigation and water extraction
This is the first 24 to 48 hours. Boarding a broken window, tarping a damaged roof, extracting standing water, and stopping the source. Most policies reimburse this separately from the repair estimate, and it's the line item carriers scrutinize hardest because it's where fraud happens. Timestamped photos and moisture readings are what get it approved.
Structural drying and dehumidification
Wet drywall, soaked carpet, saturated insulation, and wet framing all have to be dried to a documented standard - usually under 16% moisture content in wood framing - or the claim gets reopened later for mold. Drying equipment runs for 3 to 5 days on a typical Bryan storm loss. Your policy pays for the equipment, the monitoring visits, and the labor.
Repairs and rebuild
Roof decking, shingles, drywall, paint, flooring, trim, and cabinetry damaged by the storm or by the water that followed. If a limb came through the ceiling, the ceiling repair is covered. If the roof leak soaked the drywall repair Bryan TX scope, that's covered too.
Contents and additional living expenses
Furniture, electronics, clothing, and documents damaged by storm water are covered under your personal property limit - usually 50% to 70% of your dwelling coverage. If the house is uninhabitable during repairs, most policies pay for a hotel and meals up to a daily cap. Keep every receipt.
What your policy will not pay for
Every Texas homeowners policy has exclusions, and knowing them before you file saves you from a denied claim and a wasted week. The big ones:
- Ground flooding. Rising water is flood, not storm. Separate policy required.
- Neglect. If a roof leak has been dripping for months and you didn't address it, the carrier can deny the resulting mold and rot as long-term seepage.
- Mold above your limit. Most policies cap mold remediation at $5,000 to $10,000 unless you bought an endorsement. In Bryan's humidity, that cap gets hit fast.
- Outbuildings and fences. Detached garages, sheds, and fences are usually covered at a much lower sub-limit - often 10% of dwelling coverage - or excluded entirely.
- Tree removal. Most policies pay $500 to $1,000 per tree to remove a fallen tree from the structure, and nothing to remove one that fell in the yard.
- Matching. If your discontinued 2011 shingle is no longer made, some carriers pay only for the damaged slope, not the whole roof. This is worth arguing about.
Read your declarations page before you call anyone. The deductible, the mold cap, and the contents limit are all on one page, and they decide how the whole claim goes.
How much does storm damage restoration cost in Bryan?
Storm damage restoration cost in Bryan TX in 2026 runs from about $1,800 for a small roof-leak dry-out to $28,000 or more for a full storm loss with structural rebuild. The number that matters to you is the gap between the total and your deductible, because that's what insurance is actually covering.
Typical 2026 pricing in this area:
- Emergency water extraction: $1,200-$3,500 depending on square footage and how much water is standing.
- Structural drying (3-5 days, equipment + monitoring): $1,800-$5,500.
- Roof leak water damage repair: $900-$4,200 for the interior side; roof itself is separate.
- Drywall, paint, and trim rebuild: $2,500-$9,000 for a typical storm-affected room.
- Mold remediation if drying was delayed: $2,000-$12,000, and often capped by your policy.
- Full storm loss with structural rebuild: $18,000-$60,000+.
Most Bryan homeowners we work with end up paying their deductible - commonly $2,500 to $5,000 on a Texas wind/hail policy - and insurance covers the rest. If your deductible is a percentage of dwelling coverage rather than a flat dollar amount, do the math before the storm, not after.
How the claim process actually works
The claim process starts the moment you call your carrier, and the first 48 hours decide how smooth it goes. Here's the sequence that gets claims paid.
- Stop the water and make it safe. Tarp the roof, shut off the breaker to wet areas, move what you can. This is covered under your duty to mitigate.
- Photograph everything before you touch it. Wide shots of the room, close shots of the damage, a shot of the water line on the wall. Date stamps matter.
- Call your carrier and open the claim. You'll get a claim number and an adjuster assignment.
- Get emergency mitigation started. Drying can't wait for the adjuster. Most carriers reimburse emergency mitigation even if you start before the adjuster visits, as long as you document it.
- Meet the adjuster on site. Have your contractor there. This is the single biggest lever on your payout.
- Review the scope of loss. Compare it line by line against the contractor's estimate. Discrepancies get resolved with documentation, not argument.
- Repairs, then final payment. Carriers typically release depreciation after the work is complete and invoiced.
We see this every week across Bryan, especially in the older neighborhoods near Downtown and the Texas A&M campus where 1950s and 1960s homes have original plumbing and single-pane windows that fail fast in a storm. If you're in one of those houses, get the water damage cleanup Bryan TX started before the adjuster arrives - the documentation we generate during mitigation is what supports the claim.
Common mistakes that shrink your payout
The most expensive mistakes in a storm claim happen in the first 24 hours, and they're all avoidable. We've watched homeowners lose thousands by doing one of these:
- Throwing away damaged materials before the adjuster sees them. Wet carpet, ruined drywall, and soaked insulation are evidence. Photograph, then remove.
- Waiting for the adjuster before starting drying. Mold colonizes wet drywall in 24 to 48 hours. Waiting three days for an adjuster turns a $3,000 dry-out into a $9,000 mold job.
- Signing a contractor's scope without comparing it to the adjuster's. Two documents, two numbers. The gap is where money disappears.
- Not documenting contents. A photo of a wet couch is worth $0. A photo, a receipt, and a model number is worth the replacement cost.
- Assuming the carrier will find everything. Adjusters are busy after a storm. They miss things. Your contractor's documentation is what catches it.
- Hiring the first truck that shows up after a storm. Storm-chasers follow hail events through Texas. Local crews are still here in six months when the warranty call comes.
One more: don't accept a denial without reading the reason. "Long-term seepage" denials get overturned regularly when you can show the damage is recent - a dated photo, a neighbor's report, a weather record from the storm date.
When to call a professional
Call a professional when water has been sitting for more than a few hours, when the damage is inside a wall or ceiling, or when the affected area is larger than about 10 square feet. Those are the thresholds where a shop vac and a box fan stop working and mold starts.
Our team handles the whole sequence: emergency extraction, structural drying, documentation for your adjuster, and the rebuild. We work directly with Texas carriers, we photograph and meter every affected area, and we hand your adjuster a scope that matches the damage. If you want a crew that's been through Bryan storm seasons before, start with Storm Damage Restoration Bryan TX and we'll take it from there.
If the storm pushed water in through a failed roof, that's a roof leak repair Bryan TX scope on top of the interior dry-out - both covered, both documented in the same claim. If a limb took out a window and rain poured in for hours, the Emergency Water Removal Bryan TX crew is who you call first, before anything else.
Frequently Asked Questions
Does insurance cover storm damage restoration in Bryan TX?
Yes, for sudden storm damage - wind, hail, falling limbs, and rain intrusion through a failed roof or window. Standard Texas homeowners policies cover it minus your deductible. Ground flooding is excluded and requires a separate flood policy.
What does storm damage insurance cover in Bryan Texas?
Emergency mitigation, water extraction, structural drying, repairs to the structure, and damaged contents. Most policies also pay additional living expenses if the home is uninhabitable. Mold is usually capped at $5,000-$10,000 unless you added an endorsement.
How much does storm damage restoration cost in Bryan?
In 2026, small roof-leak dry-outs run $1,800-$4,000. Mid-size storm losses with drywall and flooring rebuild run $8,000-$20,000. Full structural storm losses run $18,000-$60,000+. Most homeowners pay their deductible and insurance covers the balance.
Who do I call for storm damage restoration in Bryan TX?
Call a local restoration company that handles both mitigation and rebuild, and that will meet your adjuster on site. Bryan Restoration Pros does both - we document the loss, dry the structure, and rebuild it under one claim.
How long does storm damage restoration take in Bryan?
Emergency extraction takes 1-2 days. Structural drying runs 3-5 days with daily monitoring. Repairs depend on scope: a single room is 1-2 weeks, a full storm loss is 4-10 weeks. Mold remediation adds 3-7 days if drying was delayed.
Get help with water damage restoration in Bryan
Storm damage gets more expensive every hour it sits, and the documentation window closes fast. We handle the extraction, the drying, the insurance paperwork, and the rebuild - start to finish, one crew, one claim.
Call Bryan Restoration Pros at (979) 325-7976. We're local, we answer 24/7, and we'll be on site before the mold has a chance to start.